Industry Leaders Join Together Around NY’s Most Pressing P&C Issues
In addition to my role as Chair of the Board for Big I New York, I also have the privilege of serving on the NYFirst Executive Committee. NYFirst is a coalition of independent insurance agents and property and casualty insurance carriers working together to protect the future of New York’s insurance marketplace.
Following the 2025 NYFirst P&C Insurance Summit and the passage of auto insurance tort reforms in 2026, one thing became clear: meaningful progress on the challenges facing our industry requires agents and carriers working together with a shared purpose and a unified voice.
With collaboration as our guiding principle, NYFirst evolved its structure to include an Executive Committee made up of two agent and two carrier representatives, along with a NYFirst Roundtable that brings together the full membership.
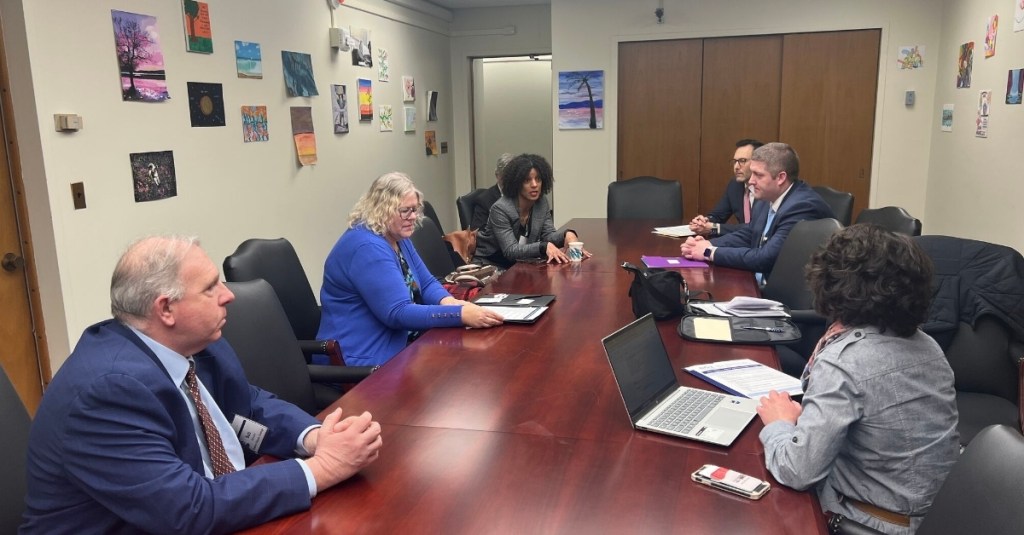
Recently, we hosted our first Roundtable meeting under the new structure, and it did not disappoint. Beyond the importance of the issues discussed, what stood out most was the level of participation. Nearly everyone around the table contributed, bringing valuable perspectives to the conversation. That kind of engagement is essential to making progress on the challenges facing our industry.
Several priorities emerged, including New York’s lengthy Department of Financial Services (DFS) filing delays, continued progress on auto insurance fraud reform, and the impact of Labor Law Sections 240 and 241 on insurance costs and affordability.
I was particularly encouraged by the shared commitment to Labor Law reform. The issue has far-reaching implications for construction insurance costs, housing affordability, and the overall cost of doing business in New York. We have an opportunity to strengthen our advocacy with more specific data and real-world examples that demonstrate the impact of these 140-year-old laws.
The discussion also reinforced the importance of maintaining momentum on auto insurance reform. As we work to address fraud and litigation abuse, continued industry engagement and support will be critical to improving New York’s insurance marketplace.
Looking ahead, I was pleased to see interest in tackling other emerging issues, including third-party litigation funding (TPLF) and joint and several liability. Both deserve thoughtful discussion and a coordinated industry perspective.
Most importantly, our first Roundtable demonstrated the value of bringing agents and carriers together around shared priorities. I’m encouraged by the level of engagement and look forward to turning these conversations into meaningful action.
Topics